The debate surrounding the digital euro is increasingly following a strange pattern.
One side warns of surveillance, programmable money, and the end of cash.
The other side summarily dismisses many of these fears as "myths."
Both sides are oversimplifying the matter.
For the digital euro is neither the already-decided surveillance euro nor simply an electronic version of a 20-euro note.
And that is precisely why it is worth looking at what is actually intended to be decided.
This is occasionally forgotten in the debate.
The legislative process is ongoing.
On July 9, 2026, the European Parliament voted 416 to 169 in favor of entering into negotiations with the Council.
Only once the legal framework is established will the ECB decide on the actual issuance. The central bank is currently working toward a possible introduction in 2029.
Many crucial details are therefore still subject to political negotiations.
This is precisely why one should neither give the all-clear for the future nor claim characteristics that have not yet been decided upon.
According to the current draft, it is indeed intended to be an additional payment option.
The ECB explicitly states that no one should be forced to use the digital euro.
Even more interesting is the parallel legislative process regarding cash.
The EU explicitly wants to strengthen its position. The Council aims to ensure a broad obligation to accept cash and to oblige member states to guarantee sufficient access to cash.
The claim that the introduction of the digital euro already signifies the decided abolition of cash is therefore incompatible with the current legal framework.
However, this does not mean that concerns about the long-term cash infrastructure are fundamentally irrational.
For law and actual payment behavior are two different things.
This is perhaps the most catchy – and at the same time most problematic – analogy.
There are similarities.
Both would be central bank money.
But cash possesses characteristics that are difficult to replicate fully in digital form.
A 50-euro note works without an account, mobile phone, power supply, or payment service provider.
And a cash payment fundamentally leaves no central electronic transaction trail.
The digital euro, on the other hand, requires a technical infrastructure.
Even a privacy-friendly offline solution must be able to prevent the same digital currency unit from being spent multiple times.
That is why even the European Data Protection Board is intensively dealing with the question of how a truly cash-like offline solution can be technically designed.
Digital cash is therefore a target vision – not a perfect technical equivalence.
Yes.
But for the most part, this is commercial bank money.
The 5,000 euros in a checking account are a claim against the bank.
The digital euro, by contrast, would be central bank money.
That is a fundamental difference.
Precisely therein lies one of the strongest arguments in favor of the digital euro:
In an increasingly cashless world, why should citizens not have digital access to public central bank money?
The question is legitimate.
Perhaps.
But this should not be treated as an already proven fact.
The current parliamentary draft contains extensive protection requirements. In particular, the ECB is not to have access to personal identification data of natural persons.
Offline payments are to be designed to be particularly privacy-friendly.
These are significant protection mechanisms.
But also the EDPB and EDPS have called for additional data protection guarantees.
The serious position is therefore:
The digital euro can be designed to be more privacy-friendly than many existing commercial payment systems. Whether it fully fulfills this promise depends on the final law and the technical implementation.
There is no evidence for this in the current legislative package.
On the contrary.
The EU is working in parallel on a regulation intended to strengthen cash acceptance and access to cash.
However, one should distinguish between two questions:
Is the abolition of cash planned?
As things stand: no.
Could the social significance of cash nevertheless decline in the long term?
Of course.
This depends significantly on the actual behavior of consumers, banks, and retailers.
This is not a myth, but one of the declared political goals.
In electronic payment transactions, Europe is heavily dependent on international private providers.
The Council explicitly cites strategic autonomy, economic security, and resilience as justifications for the digital euro.
Whether the project actually achieves these goals is, however, another question.
A political goal is not yet a proven success.
According to the currently intended model: no.
The ECB explicitly states that the digital euro is not intended to be programmable money – i.e., not money whose use can be technically restricted, for example, to certain goods, locations, or time periods.
This is important.
But here, too, the discussion may continue.
For citizens are, of course, entitled to ask what powers legislators and the central bank should possess in the long term.
The correct answer to this is a robust legal limitation.
Not the accusation that the question itself is disingenuous.
The digital euro is not intended to be an unlimited store of value.
For this purpose, maximum amounts are planned.
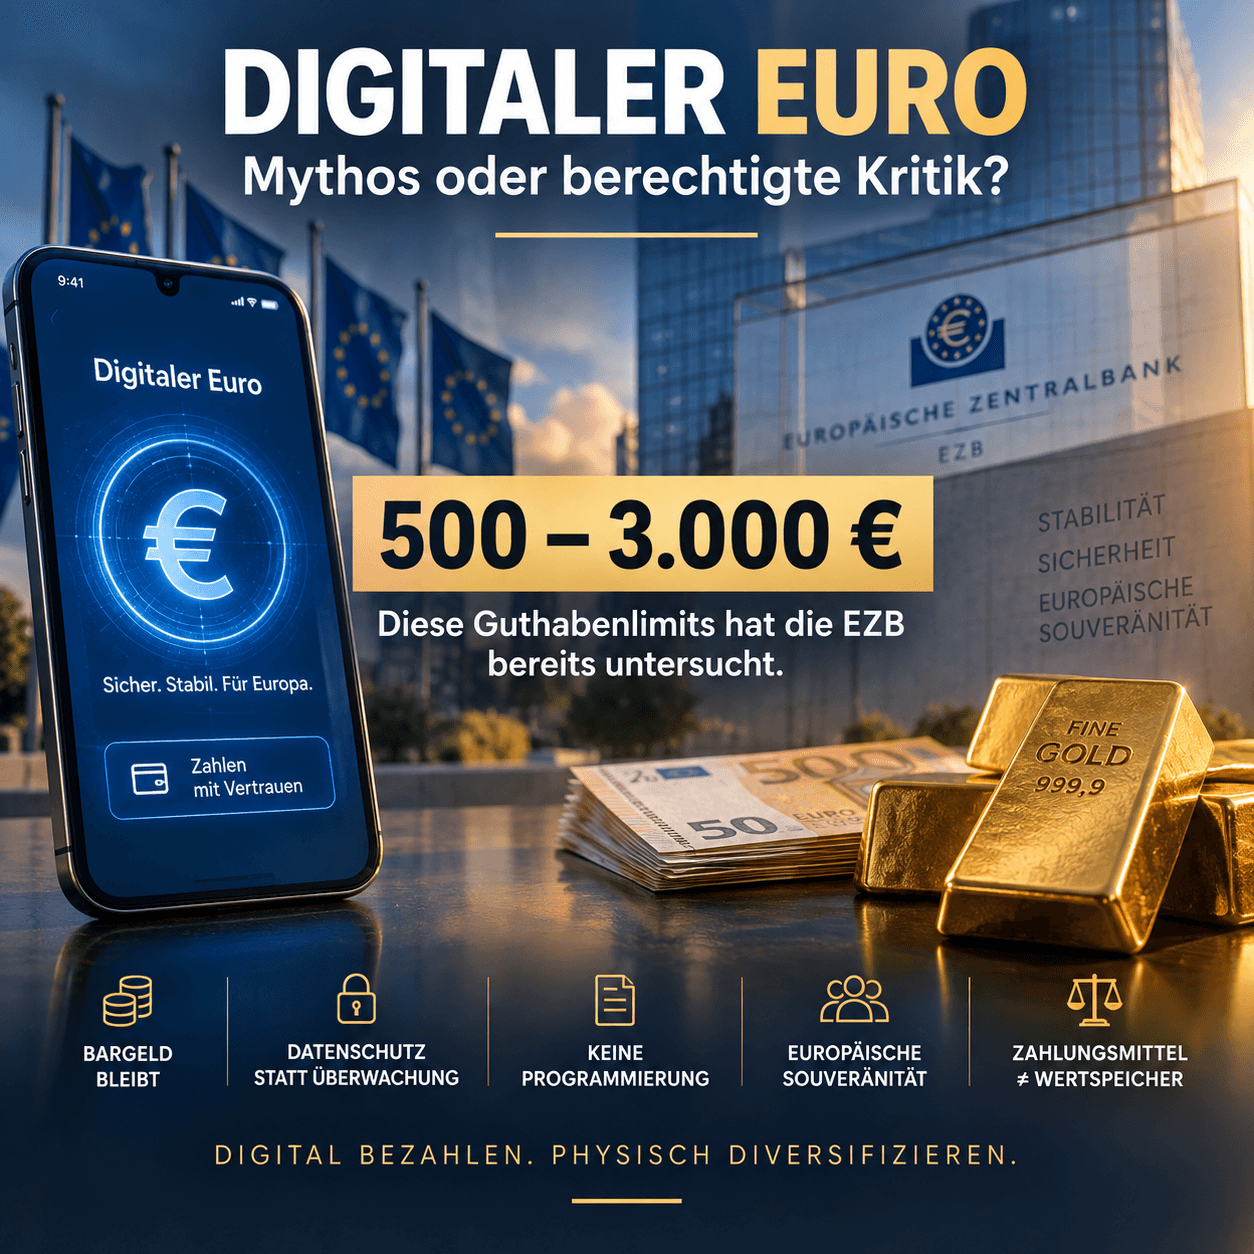
At the request of the European Parliament, the ECB has examined scenarios with upper limits between 500 and 3,000 euros. This is not yet a decision on the final amount.
The background is understandable.
If citizens could convert bank deposits into central bank money without limit, enormous sums could flow out of commercial banks very quickly during a banking crisis.
This could even accelerate a bank run.
This is precisely why the amount is to be limited.
And this is where it becomes conceptually interesting:
The digital euro is intended to be money – but deliberately not a full-fledged, unlimited store of value.
The digital euro and gold could hardly be more different.
The digital euro would be:
digital,
state central bank money,
optimized for payments,
likely limited in amount
and non-interest-bearing.
Physical gold is:
analog,
not a means of payment for daily life,
not a promise by a central bank,
not increasable by central bank decree
and, as physical possession, not dependent on a balance limit set by the ECB.
This by no means implies that gold is "better money."
Both fulfill completely different functions.
That is precisely why the comparison is interesting.
A modern economy needs efficient digital payment systems.
There is little doubt about that.
The more exciting question is:
Does every form of asset therefore also have to be completely digital?
One does not follow from the other.
Perhaps we are even witnessing two parallel developments.
Our payment transactions are becoming increasingly digital.
At the same time, central banks and private investors continue to seek assets that exist outside of purely digital claim systems.
Gold is one of them.
One does not have to reject the digital euro to ask critical questions.
And one does not have to support it to reject false claims.
The current plans contain some remarkably strong protection mechanisms.
No planned abolition of cash.
No intended purpose-specific programming.
Data protection requirements.
Offline capability.
At the same time, legitimate questions remain.
How does data protection work in practice?
How robust is the offline solution?
Who decides on balance limits in the long term?
What powers does the ECB possess?
How does the relationship between commercial banks and the central bank change?
And above all:
What rules will apply not only at the time of introduction in 2029 – but ten or twenty years later?
These are not conspiracy theories.
These are questions about the institutional architecture of our future money.
And perhaps that is exactly where we should conduct the debate.
Not:
Digital Euro – good or evil?
But rather:
What characteristics must money possess so that we can trust it even in a completely digital world?
Stay farsighted
Yours, Helge Peter Ippensen