DEAN instead of IBAN? What the new Digital Euro account number means for the Digital Euro and for Gold

September 29, 2026
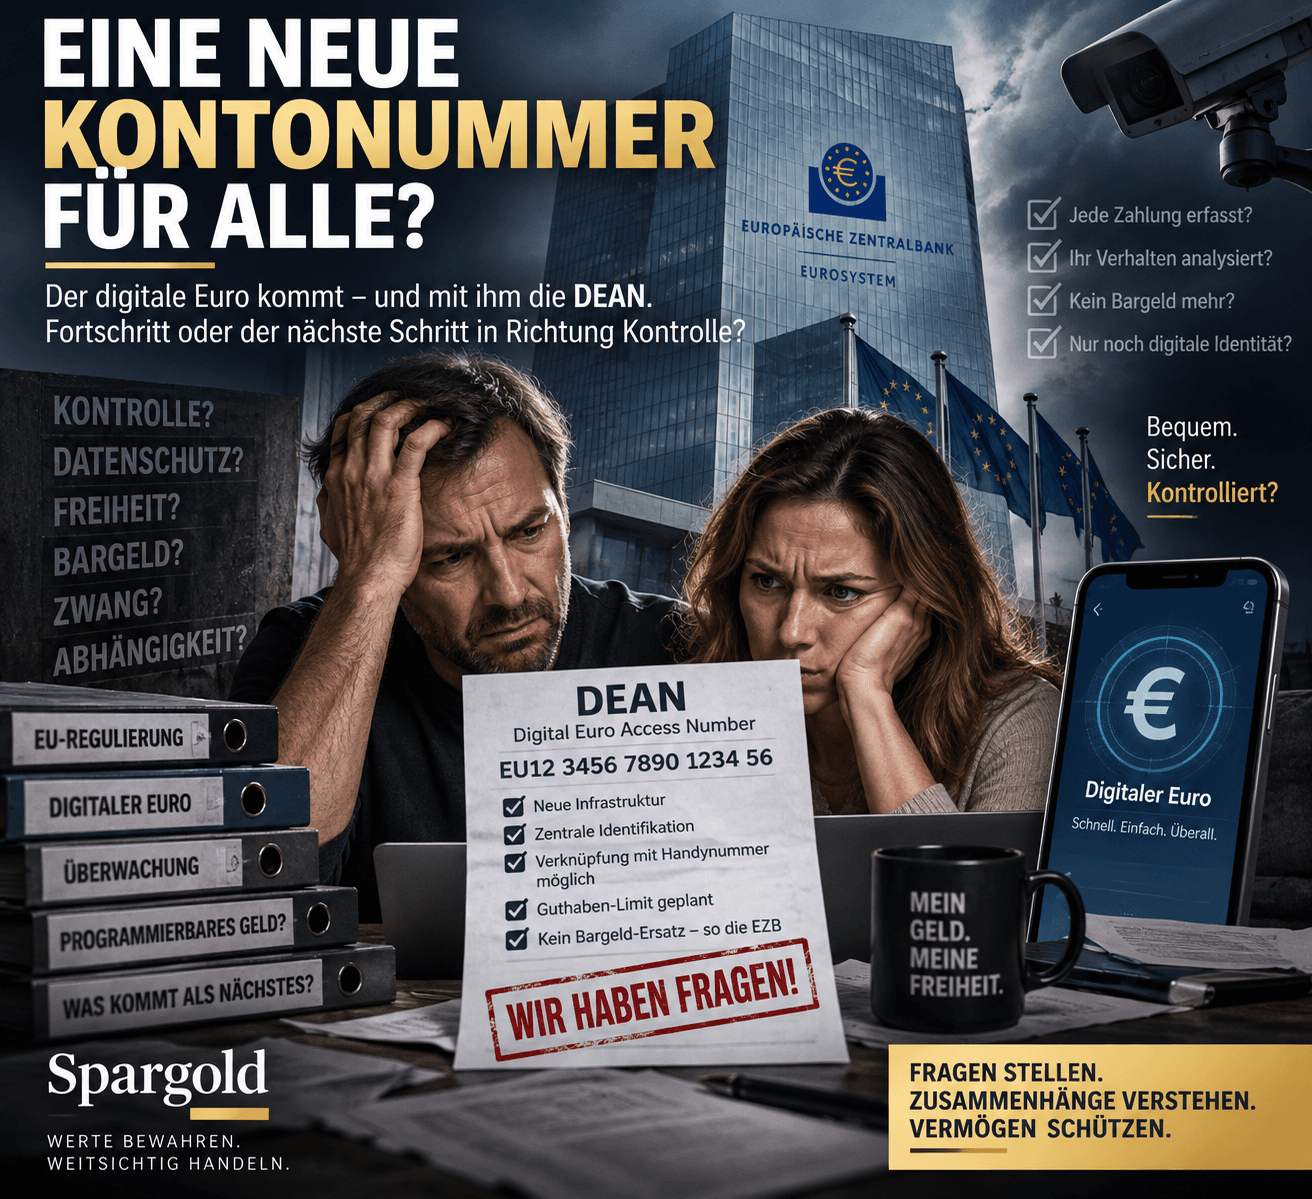

18 characters.
In the future, they could become as significant for the digital euro as the IBAN is for our current bank accounts.
The name:
Digital Euro Access Number.
While public discussion about the digital euro often revolves around fairly abstract concepts – privacy, digital central bank money, cash replacement, or programmable money –, the European Central Bank has long been building the technical infrastructure.
And that is precisely why the DEAN is interesting.
Because it shows:
The digital euro has not yet been finalized.
But technical preparations are now becoming very concrete.
To put it simply:
The IBAN identifies your bank account.
The DEAN identifies your digital euro account.
However, the comparison is not entirely accurate.
This is because two different forms of money stand behind these two account numbers.
The money in our normal current account is essentially a claim against a commercial bank.
The digital euro, on the other hand, would be:
digital central bank money.
In other words, a digital form of public money issued by the Eurosystem.
A dedicated infrastructure is being created for exactly this purpose.
This is not future speculation.
In the requirements for pilot operations published in March 2026, the ECB describes exactly how this is intended to work.
When creating a beta digital euro account, the payment service provider requests a DEAN from the Digital Euro Service Platform.
The platform generates the number.
The payment service provider assigns it to the user.
This ensures that every corresponding account has a unique identification. European Central Bank
The current draft provides for a structure of 18 alphanumeric characters.
And it begins with:
That does indeed sound a bit like an IBAN.
But it is more than just a new way of writing the same account.
This is an important point.
The DEAN is not intended to replace the IBAN.
Anyone who continues to use a traditional current account will still require the existing bank account infrastructure for it.
The DEAN belongs exclusively to the infrastructure of the digital euro.
This means that two levels could coexist in the future:
Commercial bank money → IBAN
and
Digital central bank money → DEAN
And this is where the really interesting story begins.
Today, a large part of our money is not held at the central bank.
It resides in accounts at commercial banks.
Bank balances are claims against the respective bank.
In contrast, private individuals have so far primarily had direct access to central bank money via:
Cash.
The digital euro is intended to change this.
It aims to make central bank money available digitally for daily payment transactions. European Central Bank
The DEAN would thus not merely be a new account number.
It would be a technical key to a new level of the European monetary system.
Probably not often.
This is because the ECB is also planning so-called aliases.
In pilot operations, the following is initially intended for this purpose:
Mobile phone number
The principle:
Phone number
↓
DEAN
↓
Digital euro account
The phone number would merely be the easy-to-remember alias.
In the background, the infrastructure would determine the associated DEAN and forward the payment accordingly. European Central Bank
This is important.
Because of this, the digital euro could appear much simpler in everyday life than the term “new account number” might suggest.
No.
At least not according to the current status.
This exaggeration in some headlines goes too far.
In pilot operations, a DEAN is received by those who use a corresponding beta digital euro account as a participant.
Even for a later digital euro, there are currently no plans to forcibly assign such an account to every citizen.
The ECB emphasizes:
No one should be obliged to use the digital euro. European Central Bank
Thus, the existing IBAN also remains.
And cash is also intended to remain.
At least that is the current political and regulatory design.
Because a payment system of this magnitude cannot be developed only after politicians finally say yes.
The ECB wants to be ready for a possible introduction in the year:
To this end, a twelve-month pilot operation will begin in the second half of 2027.
36 payment service providers have already been selected. European Central Bank
The development work is therefore underway now.
And that is perhaps the most important insight:
Politically, the digital euro has not yet been finally decided.
Technically, its possible introduction is already being prepared.
Both can be true at the same time.
This is where the new DEAN story directly connects to our previous analysis.
The digital euro is not intended as an unlimited savings account.
The ECB is planning a:
holding limit.
The final amount has not yet been determined.
At the request of European legislators, the ECB has examined scenarios with hypothetical limits of up to 3,000 euros per person. European Central Bank
This is not a finalized 3,000-euro limit.
But it shows the architecture.
Why a limit at all?
Because the ECB wants to prevent citizens from shifting large amounts of money from commercial bank accounts into central bank money.
This could destabilize bank financing, especially in times of crisis.
There is already a concept for this as well.
Suppose a user has 500 digital euros.
However, they want to pay 800 euros.
Then the difference could automatically come from the linked bank account.
The ECB calls this:
Reverse Waterfall.
Conversely, money that exceeds the permissible digital euro limit could be automatically forwarded to the connected commercial bank account:
Waterfall. European Central Bank
Thus, the limit would not necessarily restrict payment transactions.
It primarily limits:
how much digital central bank money can be held permanently.
And this distinction is precisely what is important.
According to the current concept:
No.
The ECB explicitly distinguishes between programmable money and conditional payments.
The digital euro is not to be designed in such a way that an authority could determine:
This money may only be spent on groceries.
Or:
This money expires in three months.
Or:
This money may not be used for certain goods.
Such earmarking is specifically not intended to be part of the digital euro. European Central Bank
In contrast, conditional payments should be possible.
For example:
Money is only transferred once a good has been delivered.
Technically, that is something different.
Here, too, it is worth distinguishing between a legitimate question and a premature assertion.
The DEAN inevitably creates a unique account identifier.
However, this does not automatically mean that the ECB can personally track every citizen and every payment with it.
The current architecture works with pseudonymization and payment service providers as interfaces.
For offline payments, the ECB even promises a level of data protection that is intended to approach that of cash: the details of an offline payment should only be known to the payer and the recipient. European Central Bank
At the same time, it remains true:
A digital payment system requires technical identifiers, access rules, software, hardware, and regulatory requirements.
This creates different dependencies than with a banknote in one's own hand.
One should be allowed to state this soberly as well.
The interesting contrast is not:
Digital euro bad – gold good.
That would be far too simple.
Both fulfill completely different functions.
The digital euro is to be optimized for:
payments.
Fast.
Digital.
Europe-wide.
With its own infrastructure.
Physical gold is quite unsuitable for this.
No one wants to pay for their coffee with 0.0008 ounces of gold.
But gold possesses properties that a digital euro deliberately does not possess.
It requires:
a technical infrastructure.
payment service providers.
identifiers such as the DEAN.
software.
rules.
holding limits.
and ultimately a functioning Eurosystem.
Physical gold does not require any of this for its mere possession.
A physical gold bar has:
no IBAN.
no DEAN.
no password.
no holding limit from the ECB.
But also:
no interest.
And its market price can fluctuate significantly.
This is not a judgment.
It describes two completely different functions.
The digitalization of our money is progressing.
This is neither surprising nor automatically threatening.
But with every new digital level, the importance of the question also increases:
And:
That is precisely where the significance of physical precious metals lies for us.
Not as a replacement for the euro.
Not as a means of payment for everyday life.
But as a possible supplement within a diversified asset structure.
Today, it appears like a technical footnote.
18 characters.
A new account identifier.
Another term alongside IBAN and BIC.
But in fact, the DEAN makes visible how concrete the architecture of the digital euro has become in the meantime.
The digital euro has not yet been introduced.
Its final design has not yet been decided.
And no one knows today how much the population would actually use it.
But the infrastructure is being prepared.
Perhaps the most interesting question is therefore not:
“Will I soon get a new account number?”
Sondern:
The answer to that will go far beyond 18 characters.
Stay far-sighted.
Yours,
Helge Peter Ippensen